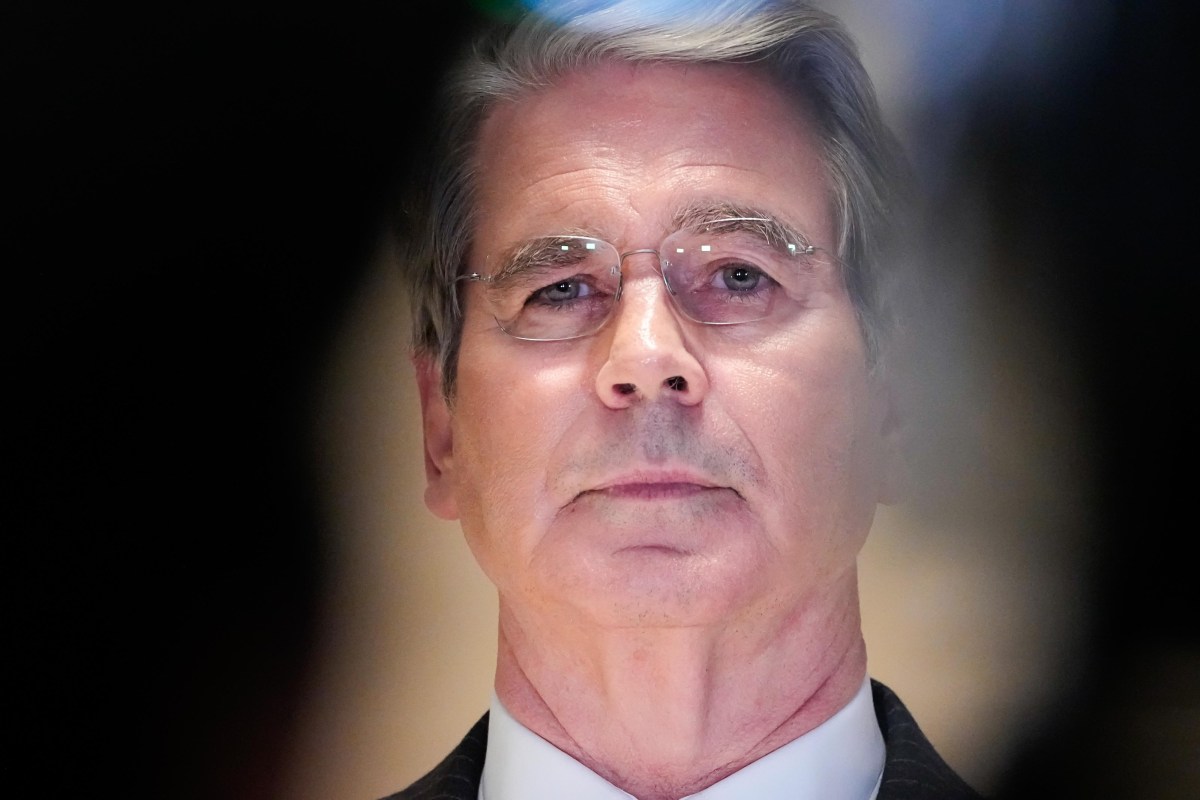
Scott Bessent had China to think about this week, and there is plenty to mull over in that relationship, but his mind may have been elsewhere.
The Treasury Secretary met Vice Premier He Lifeng ahead of Donald Trump’s summit with Xi Jinping, trade and technology top of the agenda. Bessent has been a key figure in negotiations with Beijing, assured and at times uncompromising.
He holds a wealth of market experience, specifically investment management, with expertise in currencies and fixed income. Britons who recall "Black Wednesday," in which Bessent’s group made a $1 billion fortune, still curse his name.
But, amid the China focus this week, Bessent has had another summit to worry about. Well, more of a peak, and one that shows up on the kind of financial chart very familiar to Bessent.
The 10-year Treasury yield touched 5.225 percent on Thursday, its highest point in roughly 19 years, before easing slightly. Bessent, once a master of these markets, is now struggling to best them from the other side.
Bessent’s Market
Bessent founded Key Square Capital, a global macro hedge fund, after serving as chief investment officer at Soros Fund Management.
The Treasury job fits Bessent’s expertise but reverses his position. At a hedge fund, he could take or unwind a position. As secretary, he must sell debt whether the market’s price is welcome or not.
As an investor, Bessent could choose the trade. As Treasury secretary, he is the trade. Last fall, Bessent described his job as the nation’s "top bond salesman," pointing to Treasury yields as a measure of success.
"By this metric, we are making substantial progress in keeping rates down following the spending blowout from the Biden years," Bessent said at the time.
"In fact, the U.S. Treasury market has been the best-performing developed bond market this year. The Treasury market’s total returns year to date are 6 percent—its best year since 2020.
"The U.S. 10-year term premium is basically unchanged while U.S. borrowing costs across all other areas of the curve, from 2-year notes all the way to 30-year bonds, are down year to date.
"Lower Treasury borrowing costs mean lower corporate borrowing costs, lower mortgage rates, and lower car payments—which all translates to greater affordability for all Americans."
How things have changed.
Why Bond Yields Are Rising
When Washington sells a Treasury security, it borrows money from investors and promises to repay them with interest. That security can then be resold.
Because its promised payments stay the same, its yield—the return available to a new buyer—rises when its price falls, and falls when its price rises. Higher yields make new government borrowing more expensive.
Several forces are pushing Treasury yields upward right now. The Federal Reserve raised its benchmark rate last week and said inflation remained elevated, even as it described growth as solid.
Mike Sanders, head of fixed income at Madison Investments, cited stronger data, Middle East tensions and a weak Treasury auction among the pressures.
Bond yields reflect the economy’s resilience as well as its strains. Bessent and Trump have also raised concerns with Japan about a weak yen, which may impact U.S. bond markets.
Washington’s borrowing needs increase the pressure.
The Congressional Budget Office projects $1 trillion in net interest costs this fiscal year. Trump—with costly promises like his $5,000 "dividend" for all adult Americans, a cost of around $1.2 trillion if realized—isn’t inspiring much confidence.
Current yields do not immediately reset the government’s entire debt bill, of course. Costs rise as new borrowing is issued and older debt rolls over. But a high yield that sticks would make an existing fiscal squeeze more expensive over time.
Treasury has expanded bond buybacks to improve market liquidity. It can adjust the mix of debt it issues and explain its funding plans to investors.
Those tools help market functioning and confidence, but none permits Bessent to dictate the return investors demand.
Bessent’s Treasury can manage, not set, the market.
The Cost to Borrowers
The clearest channel into consumer politics is through housing, an issue the Trump administration has sought to address in its affordability drive.
One of the reasons Trump has piled pressure on the Fed to cut rates is because it is raising costs for aspiring homeowners, shutting many out of the market because they cannot afford the mortgage costs.
Freddie Mac put the average 30-year fixed mortgage rate at 7.03 percent on Thursday, higher than a year earlier.
Mortgage rates do not track Treasurys point for point, but government bond yields help set borrowing costs for homebuyers and businesses, as Bessent acknowledged last year.
Existing fixed-rate borrowers keep their old terms, but prospective buyers face today’s price. As do those who need to remortgage.
The same channel that feeds down to voters then works in reverse. Higher yields that feed into economic pain for voters is usually expressed as a revolt at the ballot box. This year’s midterm elections in November offer the next opportunity.
The Political Test
This may be the biggest political test of Bessent’s tenure yet.
In a midterm year, higher borrowing costs risk sharpening Trump and Republicans’ cost-of-living problem, which is already going from bad to worse amid the Iran war.
Inflation and the Fed’s response lie beyond Treasury’s control. Spending and taxes also involve Congress. The Treasury secretary can keep the market functioning, but easing the pressure on borrowers depends on more than his skill as a trader.
Bessent spent his career spotting macroeconomic turning points. Now he stands squarely on the other side of the trade, with a political reputation to defend as well as a financial one.
The 10-year’s peak is no summit he wants to conquer. His job is to find a way back down. And this time, he cannot simply sell the position.